50-30-20 Budget Rule: How It Works on an Indian Salary
The 50-30-20 budget rule splits take-home pay into needs, wants and savings. See how it works on an Indian salary, with worked examples and metro-city tweaks.
In this article
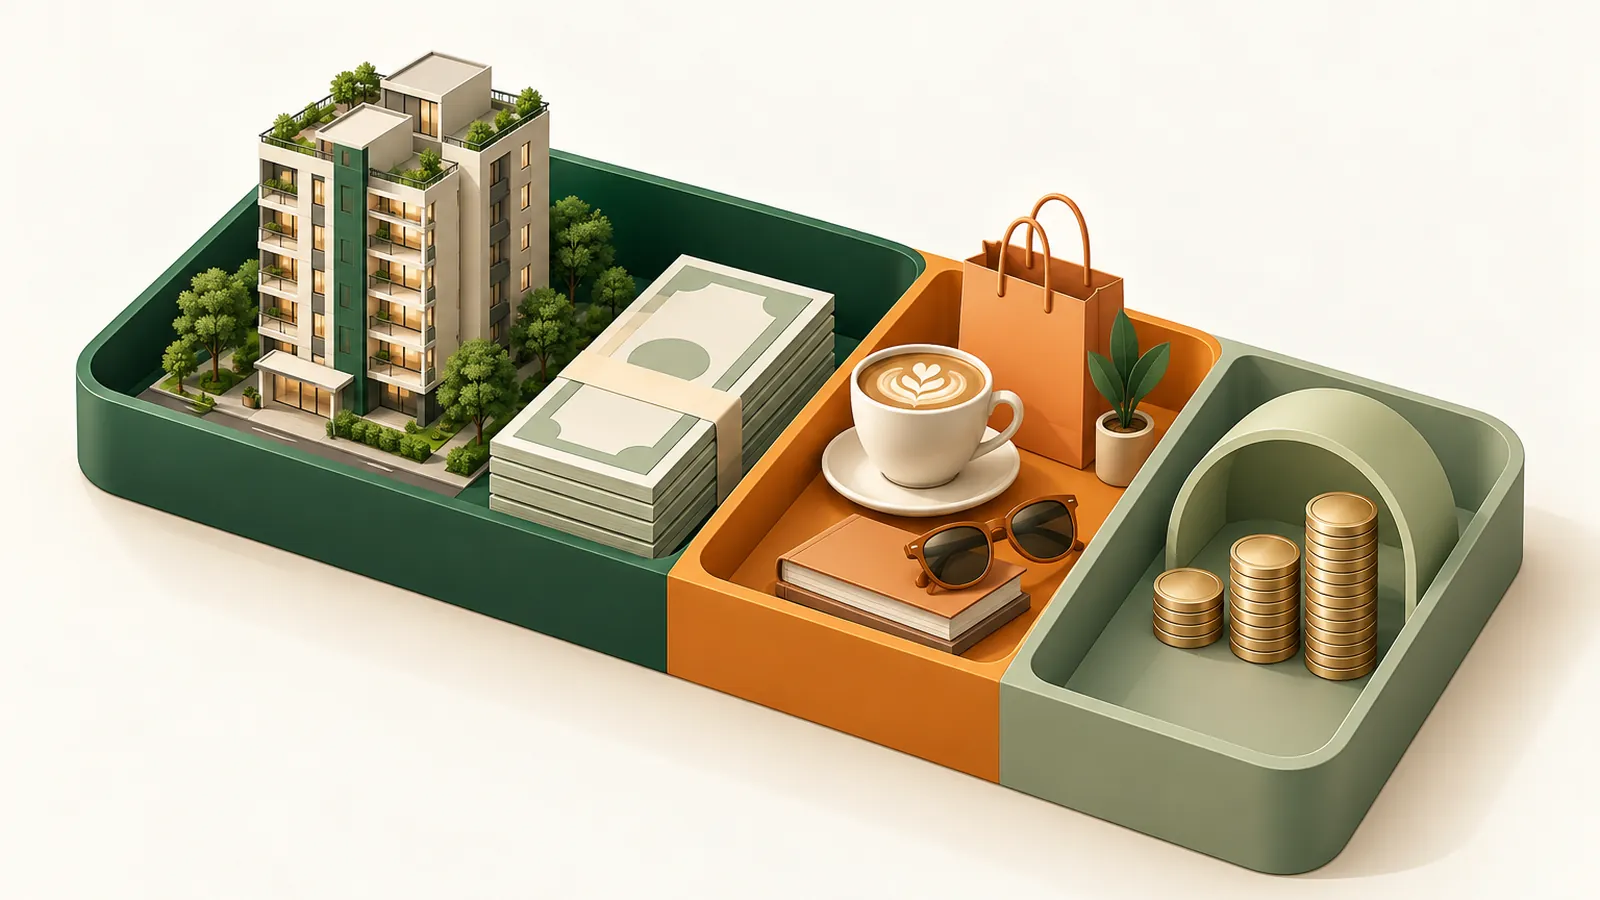
The 50-30-20 budget rule divides your take-home salary into three buckets: 50% for needs, 30% for wants and 20% for savings and extra debt repayment. On a ₹60,000 in-hand salary, that is ₹30,000 for needs, ₹18,000 for wants and ₹12,000 for savings. In Indian metros, where rent is high, many people adapt it to 60-20-20, but the principle is the same: decide your savings first and give every rupee a job.
The three buckets explained
50% Needs
Expenses you must pay to live and work, and that would cause real harm if skipped:
- Rent or home loan EMI
- Groceries and basic household items
- Electricity, water, gas, mobile and internet
- Commute to work
- Minimum EMIs on existing loans and minimum credit card dues
- Health and term insurance premiums
- School fees and essential childcare
30% Wants
Spending that improves life but could be cut in a crunch:
- Eating out and food delivery
- OTT subscriptions, gaming, hobbies
- Clothes and gadgets beyond the basics
- Holidays and weekend trips
- Upgrades, such as a bigger flat than you need or a premium phone plan
20% Savings and debt repayment
Money that builds your future:
- Emergency fund contributions
- SIPs in mutual funds, PPF, NPS, RDs
- Saving for goals such as a down payment or a child's education
- Extra loan prepayments over the required EMI
Your employee PF deduction is already taken out before take-home pay, so treat it as retirement saving on top of the 20%.
Worked example: ₹60,000 take-home salary
| Bucket | Share | Amount (₹) | How it might be used |
|---|---|---|---|
| Needs | 50% | 30,000 | Rent ₹16,000; groceries ₹7,000; utilities ₹2,500; commute ₹2,500; insurance ₹2,000 |
| Wants | 30% | 18,000 | Dining ₹6,000; shopping ₹5,000; OTT and hobbies ₹2,000; travel fund ₹5,000 |
| Savings | 20% | 12,000 | Emergency fund ₹4,000; equity SIP ₹8,000 |
| Total | 100% | 60,000 |
What the 20% can grow into
Suppose the full ₹12,000 a month goes into an SIP for 15 years. At an illustrative 10% annual return, which is not guaranteed:
- Total invested: ₹12,000 × 180 months = ₹21.6 lakh
- Illustrative value after 15 years: about ₹50.2 lakh
Run your own numbers on the SIP calculator. Market-linked returns vary, and equity can fall sharply in some years.
Adapting 50-30-20 to Indian realities
The rule was designed for US households. In India, a few things change the maths.
High metro rents
A one-bedroom flat in many parts of Mumbai or Bengaluru can take 35-45% of an entry-level salary on its own. Forcing needs into 50% may be impossible. Options:
| Variant | Needs | Wants | Savings | When it fits |
|---|---|---|---|---|
| 50-30-20 | 50% | 30% | 20% | Moderate rent, few EMIs |
| 60-20-20 | 60% | 20% | 20% | Metro rent, single earner |
| 60-25-15 | 60% | 25% | 15% | First job, high rent (temporary) |
| 40-30-30 | 40% | 30% | 30% | Living with family, aggressive goals |
| 70-10-20 | 70% | 10% | 20% | Heavy EMIs or dependants (temporary) |
Cut wants before savings. If needs exceed 60% for long, review whether rent, a car loan or other EMIs are too large.
Family support
Many Indian earners send money home to parents or siblings. If it is non-negotiable, treat it as a need. If it varies, budget a fixed amount and keep it under needs so it does not crowd out savings.
Annual and festival expenses
Diwali, weddings, school admissions and insurance renewals arrive in lumps. Spread them: estimate the yearly total, divide by 12 and include it in needs or wants every month.
High-interest debt
If you carry credit card dues, which commonly cost about 30-45% a year, push extra money into repaying them from the 20% bucket before increasing SIPs. Our guide on whether to pay off debt or invest first explains the trade-off.
How to put 50-30-20 into practice
- Find your take-home pay. Use the actual credit in your salary account. If you are unsure how in-hand differs from CTC, see CTC vs gross vs take-home salary.
- Track one month of spending and tag each item as need, want or saving. Our guide on how to track monthly expenses covers apps and simple spreadsheets.
- Automate the 20%. Set SIP dates and standing instructions 1-3 days after salary day.
- Use two accounts. Keep needs and wants spending in the salary account, and move savings to a separate account.
- Review monthly. If wants overshoot, cut them the following month instead of dipping into savings.
- Raise savings with every hike. Moving from 20% to 25-30% over time makes a big difference.
50-30-20 at different salary levels
The same percentages give very different rupee amounts. Here is the basic split for common take-home salaries:
| Take-home pay (₹) | Needs 50% (₹) | Wants 30% (₹) | Savings 20% (₹) |
|---|---|---|---|
| 25,000 | 12,500 | 7,500 | 5,000 |
| 40,000 | 20,000 | 12,000 | 8,000 |
| 75,000 | 37,500 | 22,500 | 15,000 |
| 1,00,000 | 50,000 | 30,000 | 20,000 |
| 1,50,000 | 75,000 | 45,000 | 30,000 |
At lower salaries, needs often take more than half, so a 60-25-15 or 65-20-15 split may be the honest starting point. At higher salaries, needs usually take a smaller share, and keeping wants at 30% can mean lifestyle spending of ₹45,000 or more a month. That is a good point to move towards 30% savings instead. A useful habit is to send at least half of every increment straight to the savings bucket, so your savings rate rises automatically as income grows while your lifestyle still improves.
Common mistakes with the 50-30-20 rule
- Calling wants needs. A car loan for a premium SUV or a ₹1,500 phone plan is partly a want.
- Ignoring EMIs. Count every EMI under needs. If EMIs alone exceed 30-35% of take-home pay, the budget will feel tight whatever rule you use. Check new loans on the EMI calculator first.
- Saving whatever is left at month-end. It is usually nothing. Save first.
- Treating the rule as fixed. It is a starting framework; adjust percentages as income, city and family change.
- Skipping the emergency fund. Before investing for long-term goals, build a cushion of 3-6 months of essential expenses. See how much emergency fund you need.
Is 50-30-20 right for you?
It works well if you want a simple, low-effort system and do not want to track every rupee. It may be too loose if you have a big near-term goal or significant debt, and too tight if your rent is high relative to income. In those cases, use a tighter variant or a detailed category budget like the ones in our salary budget guide.
Key takeaways
- The 50-30-20 rule splits take-home pay into 50% needs, 30% wants and 20% savings and extra debt repayment.
- Apply it to in-hand salary; employee PF is extra retirement saving.
- In Indian metros, 60-20-20 is often more realistic; cut wants before savings.
- Automate the savings bucket on salary day and clear high-interest debt first.
- Treat the rule as a starting point and raise your savings share with each increment.
Frequently asked questions
What is the 50-30-20 budget rule?
It is a simple budgeting guideline that puts 50% of take-home pay towards needs, 30% towards wants and 20% towards savings and debt repayment beyond minimum payments. It was popularised in the US book All Your Worth by Elizabeth Warren and Amelia Warren Tyagi.
Does the 50-30-20 rule work in Indian metro cities?
Often not exactly. High rents in cities such as Mumbai, Bengaluru or Delhi can push needs to 60% or more of a modest salary. A 60-20-20 or 60-25-15 split is a reasonable starting point as long as savings stay protected.
Are EMIs a need or a want under the 50-30-20 rule?
The minimum EMI on any existing loan is a need, because missing it hurts your credit score. Extra prepayments on loans count in the 20% savings and debt bucket.
Is the 50-30-20 rule calculated on gross or net salary?
On net, or take-home, salary: the amount credited to your account after employee PF, professional tax and TDS. Employer and employee PF contributions are additional retirement savings on top of the 20%.
Is 20% savings enough?
For many people starting out, 20% is a solid base. If you start investing late, have a big goal such as a home down payment, or plan to retire early, you may need 30% or more.
This article is for general education and is not personalised financial, tax or legal advice. Rates and rules are as of 19 Oct 2026; confirm current terms with your lender, AMC or a qualified adviser.