Cash Conversion Cycle: Formula, Example and How to Cut It
Cash conversion cycle for Indian MSMEs: DIO, DSO and DPO formulas, a worked ₹ example freeing ₹31 lakh, and how the MSME 45-day rule limits DPO.
In this article
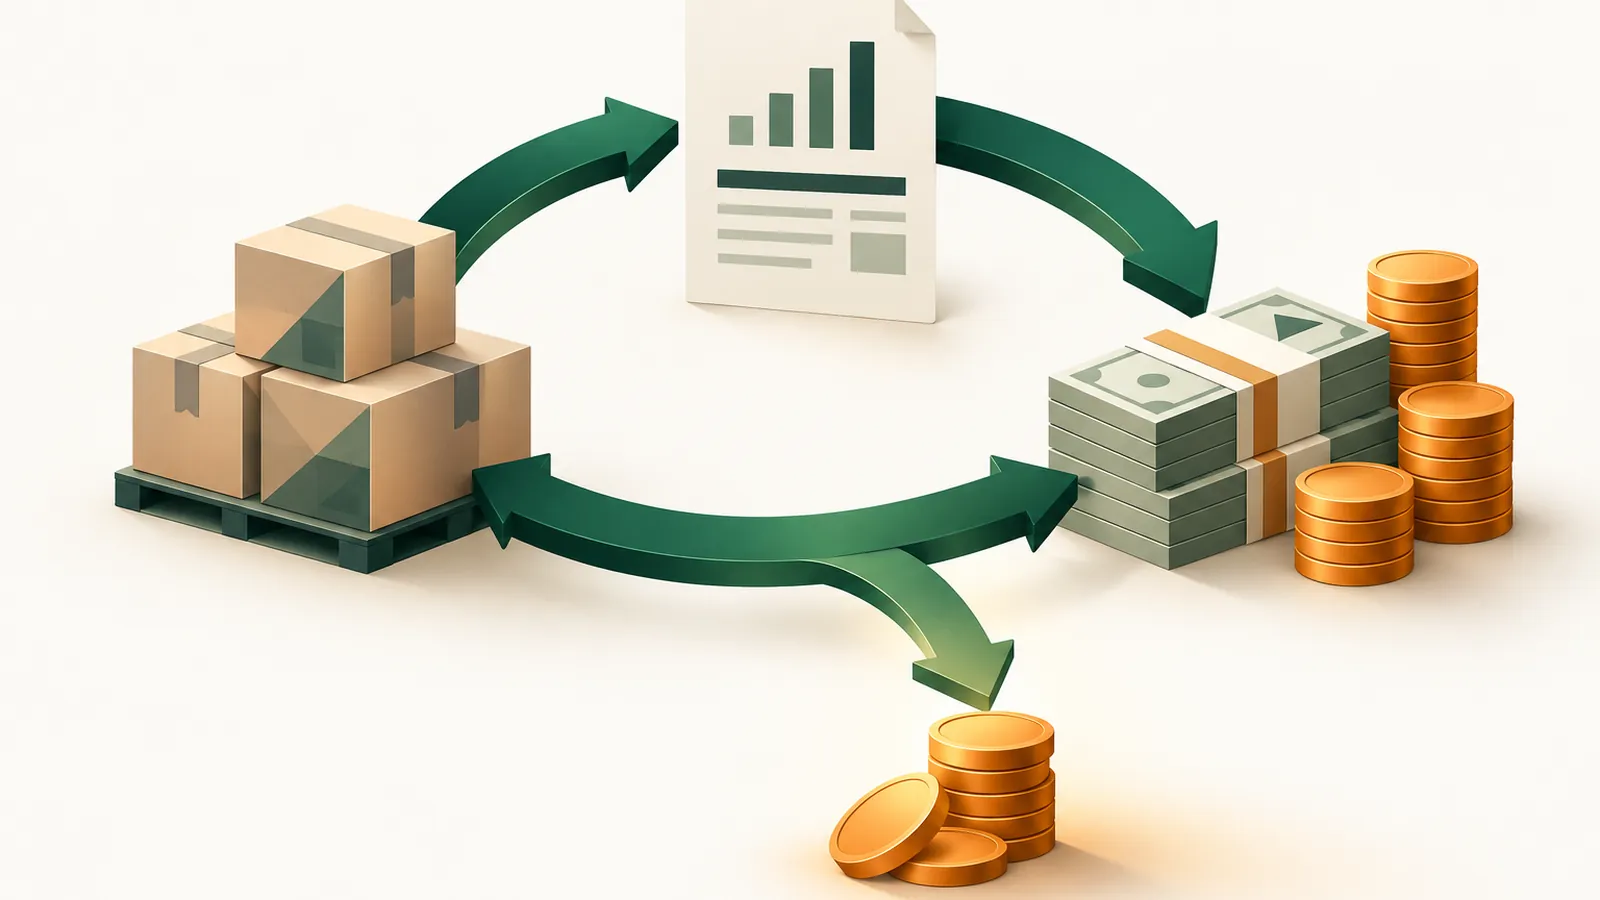
The cash conversion cycle (CCC) tells you how many days your money is stuck between paying for stock and collecting cash from customers: CCC = inventory days + receivable days − payable days. A business with a 90-day cycle needs to fund roughly three months of costs from its own capital or a bank limit, so every day you cut releases cash. This guide shows how to calculate it from your books and which levers actually work for an Indian MSME.
The three parts of the cycle
| Component | Formula | What it measures |
|---|---|---|
| Days inventory outstanding (DIO) | Average inventory ÷ Cost of goods sold × 365 | How long stock sits before it is sold |
| Days sales outstanding (DSO) | Average receivables ÷ Credit sales × 365 | How long customers take to pay |
| Days payable outstanding (DPO) | Average payables ÷ Cost of goods sold × 365 | How long you take to pay suppliers |
| Cash conversion cycle | DIO + DSO − DPO | Days your own money is tied up |
Use annual figures with 365 days, or monthly figures with 30 days; just be consistent. "Average" is ideally (opening + closing) ÷ 2, or an average of month-end balances if your stock swings a lot. Use figures excluding GST for sales and cost, but note that receivables and payables in your ledger usually include GST; for a rough analysis that difference is acceptable as long as you are consistent across months.
The cycle is a timing measure, not a profit measure. A business can be profitable and still run short of cash if its cycle is long, which is the core idea in profit vs cash flow.
Worked example: an electrical goods distributor
The figures are illustrative. A Pune distributor of switches, wires and fittings has these numbers for FY 2025-26:
- Annual sales (all on credit): ₹3.65 crore
- Cost of goods sold: ₹2.92 crore (80% of sales)
- Average inventory: ₹48 lakh
- Average receivables: ₹60 lakh
- Average payables: ₹24 lakh
Step 1 — DIO. ₹48 lakh ÷ ₹292 lakh × 365 = 60 days.
Step 2 — DSO. ₹60 lakh ÷ ₹365 lakh × 365 = 60 days.
Step 3 — DPO. ₹24 lakh ÷ ₹292 lakh × 365 = 30 days.
Step 4 — CCC. 60 + 60 − 30 = 90 days.
Net working capital tied up in this cycle = inventory + receivables − payables = ₹48 lakh + ₹60 lakh − ₹24 lakh = ₹84 lakh.
To make the cycle tangible, convert days into rupees:
- One day of sales = ₹365 lakh ÷ 365 = ₹1 lakh
- One day of cost of goods = ₹292 lakh ÷ 365 = ₹80,000
So each day of DSO is worth ₹1 lakh of cash, and each day of DIO or DPO is worth ₹80,000.
What a 35-day improvement is worth
Suppose the distributor sets three targets for the coming year:
| Lever | From | To | Days saved | Cash released |
|---|---|---|---|---|
| Collect faster (DSO) | 60 days | 45 days | 15 | 15 × ₹1,00,000 = ₹15,00,000 |
| Hold less stock (DIO) | 60 days | 50 days | 10 | 10 × ₹80,000 = ₹8,00,000 |
| Pay suppliers later (DPO) | 30 days | 40 days | 10 | 10 × ₹80,000 = ₹8,00,000 |
| Total | 90 days | 55 days | 35 | ₹31,00,000 |
Check: new inventory ₹40 lakh + receivables ₹45 lakh − payables ₹32 lakh = ₹53 lakh, down from ₹84 lakh.
If that ₹31 lakh was being funded through a cash credit account at an illustrative 12% a year, the interest saving is ₹31,00,000 × 12% = ₹3,72,000 a year. That flows straight to profit, without selling a single extra unit.
Lever 1: collect faster (DSO)
- Invoice the same day goods are dispatched, with the PO number, e-way bill and correct GSTIN, so the buyer's accounts team has no reason to hold it.
- Agree credit terms in writing and print the due date, not just "30 days", on every invoice.
- Run a weekly ageing report of receivables in 0–30, 31–45, 46–60 and 60+ day buckets, and call before the due date, not after.
- Offer a small early-payment discount only after checking its true cost; a 2% discount for paying 20 days early is expensive, as shown in cost of 30-day credit terms.
- Use your MSME status. If your business is a micro or small enterprise registered on the Udyam portal, buyers must pay you within the agreed period, capped at 45 days, under Section 15 of the MSMED Act, 2006. Delayed amounts attract compound interest at three times the RBI Bank Rate under Section 16, and you can approach the MSME Samadhaan portal. Mention your Udyam number on invoices.
- Discount large-buyer invoices on TReDS or with an invoice-discounting lender, which converts receivables to cash in days; see invoice discounting vs factoring.
Lever 2: hold less stock (DIO)
- Classify items into A (top 20% of SKUs by value, usually about 80% of stock value), B and C. Review A items weekly.
- Set reorder levels using actual sales velocity, not habit. Slow movers older than 90 days should be cleared even at a small loss; the cash is worth more than the stock.
- Negotiate smaller, more frequent deliveries with key suppliers. A slightly higher unit price can still be cheaper once interest on idle stock is counted.
- Seasonal traders need a different approach; see inventory planning for a seasonal business.
Lever 3: pay later, within the law (DPO)
Stretching suppliers is the easiest lever on paper and the most constrained in practice.
The MSME 45-day rule. If a supplier is a micro or small enterprise (registered on Udyam, and a manufacturer or service provider), you must pay within the agreed credit period, which cannot exceed 45 days from acceptance of goods or services, and within 15 days where there is no written agreement. Under old Section 43B(h) of the Income-tax Act, 1961, introduced from FY 2023-24, an amount owed to such a supplier beyond this limit is deductible only in the year you actually pay it. The Income-tax Act, 2025, which applies from 1 April 2026, carries the same rule in Section 37(2)(g), as confirmed in a Finance Ministry reply in the Rajya Sabha in July 2026. Interest paid under Section 16 of the MSMED Act is not deductible at all.
As of October 2026, the MSME classification uses the limits notified from 1 April 2025: micro is investment up to ₹2.5 crore and turnover up to ₹10 crore; small is up to ₹25 crore and ₹100 crore. Wholesale and retail traders can register on Udyam, but that registration is meant for priority-sector lending, and the tax disallowance is widely understood not to apply to purchases from them. Check each supplier's Udyam certificate for its category and activity.
In practice: negotiate longer terms with large non-MSE suppliers, keep MSE suppliers within 45 days, and track MSE dues separately in your accounting software. Payment terms are also a relationship; stretching a critical supplier can cost you priority, quality or price.
Where the cycle stands across business types
| Business type | Typical DIO | Typical DSO | Typical DPO | Resulting CCC |
|---|---|---|---|---|
| Kirana or supermarket | Short | Near zero (cash/UPI) | Moderate | Short or negative |
| Restaurant | Very short | Near zero | Moderate | Negative |
| FMCG distributor | Moderate | Moderate | Short to moderate | Moderate |
| Engineering manufacturer | Long (raw material + WIP) | Long | Moderate | Long |
| Marketplace seller | Moderate | Short (settlement cycle) | Short | Moderate |
These are broad patterns, not benchmarks. Compare your own cycle month by month first; the trend tells you more than an industry average.
How to fund the cycle that remains
Every business has some cycle to fund. The right tool is usually a working capital limit (cash credit or overdraft) sized to the cycle, not a term loan. Our comparison of working capital loan vs term loan explains why. Banks often assess your limit using the same numbers: projected inventory and receivables, minus trade creditors, minus a margin you bring in yourself.
Key takeaways
- CCC = DIO + DSO − DPO; it measures how long your own cash is locked up in operations.
- Convert days into rupees: one day of DSO is worth one day of sales.
- In the illustrative example, cutting the cycle from 90 to 55 days released ₹31 lakh and saved ₹3.72 lakh a year of interest at 12%.
- Collections and stock discipline usually give the biggest, safest gains.
- Pay micro and small suppliers within 45 days; late dues are deductible only on payment under Section 37(2)(g) of the Income-tax Act, 2025 (old Section 43B(h)).
- Fund the remaining cycle with a working capital limit, not long-term debt.
Frequently asked questions
What is the cash conversion cycle formula?
Cash conversion cycle equals days inventory outstanding plus days sales outstanding minus days payable outstanding. It measures how many days your cash stays locked in stock and customer dues before it comes back.
What is a good cash conversion cycle?
Shorter is better, but a good figure depends on the industry. Grocery retailers and restaurants can run near zero or even negative, while manufacturers and distributors selling on credit often run 60 to 120 days.
Can the cash conversion cycle be negative?
Yes. If customers pay you before you have to pay suppliers, as in many supermarkets and e-commerce platforms, the cycle is negative and suppliers effectively fund your working capital.
Can I delay paying MSME suppliers to improve my cash cycle?
Only up to a point. Under the MSMED Act you must pay micro and small suppliers within the agreed period, which cannot exceed 45 days. Late amounts are deductible only on payment under Section 37(2)(g) of the Income-tax Act, 2025, the successor to old Section 43B(h).
How is the cash conversion cycle different from the operating cycle?
The operating cycle is inventory days plus receivable days, the full time from buying stock to collecting cash. The cash conversion cycle subtracts the days you take to pay suppliers, so it shows only the part you must fund yourself.
This article is for general education and is not personalised financial, tax or legal advice. Rates and rules are as of 19 Oct 2026; confirm current terms with your lender, AMC or a qualified adviser.